Nasdaq-100: Constituents, Eligibility Rules and Index Changes

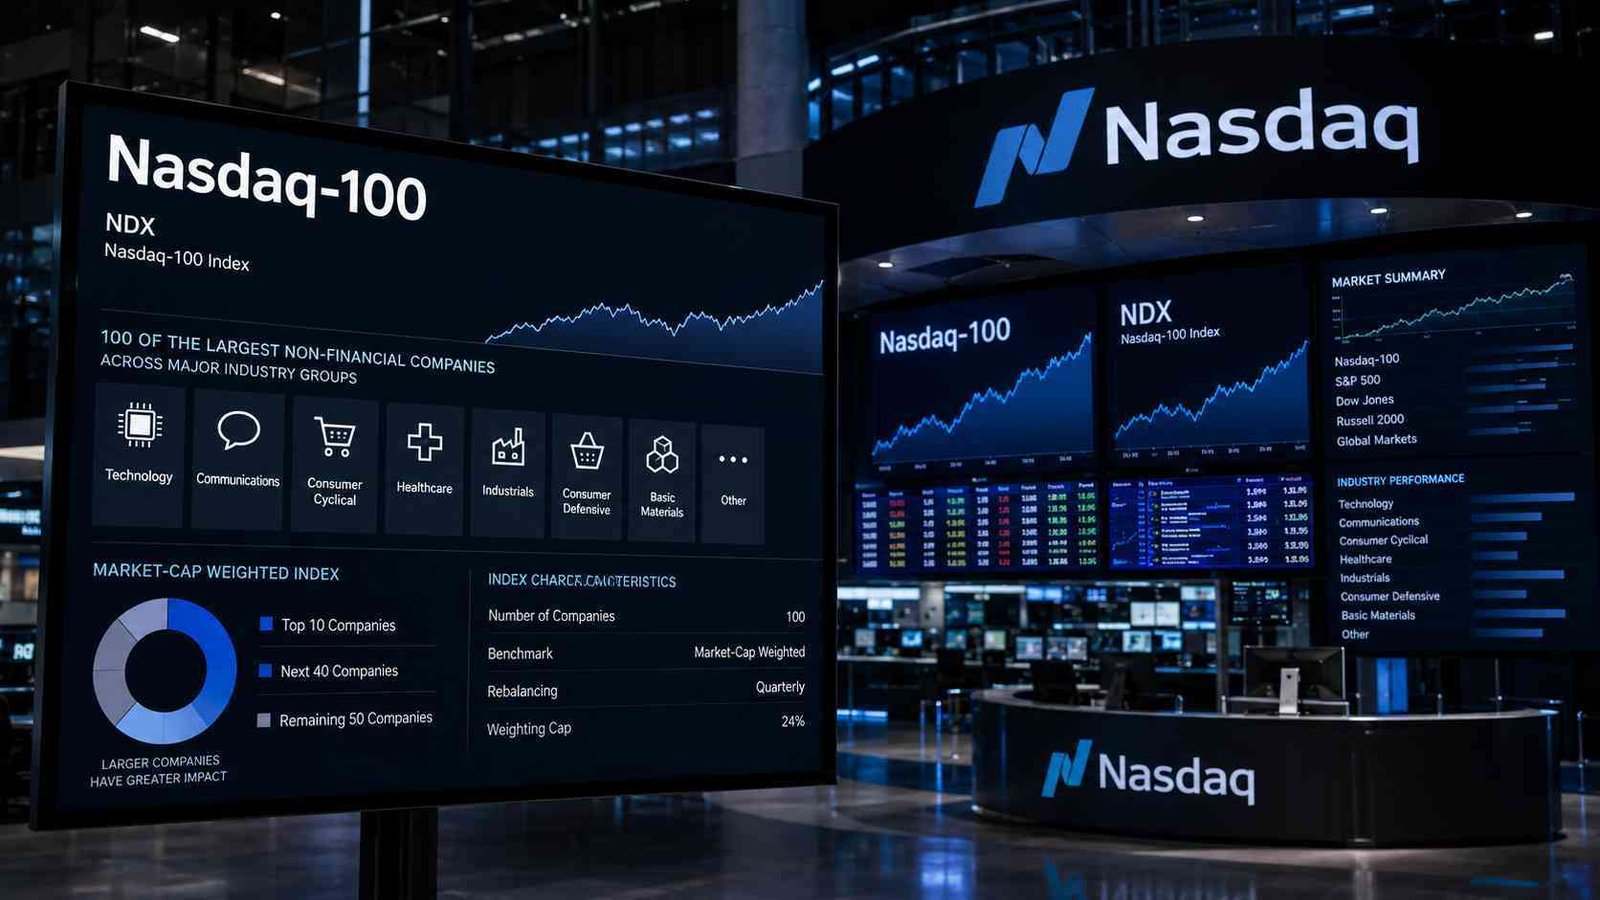
The Nasdaq-100 is a stock market index built around 100 of the largest non-financial companies listed on Nasdaq-affiliated U.S. exchanges. It is widely associated with large technology and growth companies, but the index is broader than a technology benchmark. Its rules also allow companies from industries such as retail, healthcare, biotechnology and telecommunications to qualify.
What makes the Nasdaq-100 especially useful to understand is that being one of the largest companies on Nasdaq is not, by itself, enough to guarantee inclusion. Companies must meet eligibility requirements, pass liquidity and listing tests, and fit the index’s selection rules. Once selected, companies also do not receive equal weights. The index uses a modified market-capitalization approach designed to limit how much influence its largest constituents can have.
That makes the Nasdaq-100 different from the broader Nasdaq Composite. The Composite covers thousands of eligible Nasdaq-listed securities, while the Nasdaq-100 concentrates on a much smaller group of large non-financial companies.
What Is the Nasdaq-100?
The Nasdaq-100, identified by the ticker NDX, measures the performance of 100 of the largest Nasdaq-listed non-financial companies. Nasdaq describes it as a modified market-capitalization-weighted index.
The index was launched in January 1985 alongside the Nasdaq Financial-100. The Nasdaq-100 was designed to represent major non-financial companies listed on Nasdaq, while the separate Financial-100 covered financial stocks.
The name can be misleading if it is interpreted as simply “the 100 biggest companies on Nasdaq.” The selection process includes several rules beyond company size.
For example, eligible securities must generally be listed on a U.S. Nasdaq-affiliated exchange, meet liquidity requirements, and satisfy other eligibility conditions. Financial companies classified under the Industry Classification Benchmark are excluded. REITs and SPACs are also not eligible under the current methodology.
The result is a concentrated large-company index rather than a complete representation of everything traded on Nasdaq.
Which Companies Can Enter the Nasdaq-100?
Market capitalization is important, but it is only one part of the process.
The current methodology allows eligible common stocks, tracking stocks and American Depositary Receipts, including both primary and non-primary ADR structures. Multiple share classes from the same company can also qualify if they satisfy the other requirements.
A company must be primarily listed on a qualifying U.S. Nasdaq-affiliated exchange. The Nasdaq Capital Market is excluded from this particular listing rule. It also must not be classified in the Financial Industry under the ICB system used by Nasdaq for index classification.
There is no fixed minimum or maximum market-capitalization threshold stated as an eligibility requirement. Instead, market capitalization plays a central role when eligible companies are ranked and selected.
Liquidity matters as well. Under the current methodology, a security generally needs a three-month average daily value traded of at least $5 million. Newer securities have separate rules for satisfying the trading-history requirement.
This is an important distinction: a company can be very large and still fail to qualify if it does not satisfy the index’s other rules.
How the Nasdaq-100 Selects Its 100 Companies
The main selection process happens during the annual December reconstitution.
Eligible companies are ranked by full market capitalization using the methodology’s reference date. Nasdaq then applies a defined selection sequence rather than simply taking the first 100 names on the ranking list.
The annual process begins by selecting the top 75 ranked companies.
Current Nasdaq-100 constituents that rank within the top 100 are then retained if they were not already selected in the first step. Existing constituents ranked from 101 through 125 can also receive protection under specified conditions, including whether they were inside the top 100 at the previous reconstitution or were added after that reconstitution.
Finally, eligible companies within the top 100 that are not already constituents can be selected until the index reaches 100 constituents.
This helps explain why the Nasdaq-100 should not be thought of as a simple yearly list of ranks 1 through 100.
The rules provide continuity for existing members while still allowing the index to reflect changes in the size of eligible companies.
Why the Nasdaq-100 Is Not Equal-Weighted
The 100 companies in the index do not each receive a 1% weight.
The Nasdaq-100 uses a modified market-capitalization weighting system. In a basic market-cap-weighted index, a company with a larger market value has a larger influence on the index. The Nasdaq-100 starts from that general principle but applies additional limits to reduce concentration.
The weighting process uses modified market capitalization rather than simply assigning weight according to every share a company has outstanding.
For example, the current methodology places limits on how low-float securities are treated. For weighting purposes, the total shares outstanding of a low-float security can be capped at three times its free-floating shares.
After the initial weights are calculated, Nasdaq applies additional company-level and security-level constraints.
At the annual reconstitution, if a company’s initial weight is above 24%, the methodology first adjusts company weights so that no company exceeds 20%. It then applies a second company-level test to the group of companies with weights above 4.5%.
There are also security-level controls. If a security’s initial weight exceeds 15%, the methodology adjusts the weighting so that no security exceeds 14%. The five largest resulting security weights are then tested against an aggregate limit, with additional caps applied when necessary.
The practical takeaway is simple: larger companies generally matter more, but the largest companies cannot take unlimited control of the index.
When Does the Nasdaq-100 Change?
The Nasdaq-100 has both an annual reconstitution and scheduled quarterly rebalances.
The annual reconstitution takes place in December. This is when the broader selection process determines which companies belong in the index for the coming period.
Regular rebalances occur in March, June and September. These adjustments update index shares and account for changes in company size, shares outstanding and other factors specified by the methodology.
The quarterly process can also change constituents when companies no longer meet the applicable ranking and eligibility requirements.
For example, Nasdaq’s June 2026 quarterly changes added Astera Labs, CoreWeave, Nebius Group, Rocket Lab and Teradyne while removing Charter Communications, Cognizant Technology Solutions, Insmed, Verisk Analytics and Zscaler. The changes became effective before the market opened on June 22, 2026.
That example shows why a Nasdaq-100 components list should always be treated as time-sensitive rather than permanent.
Why Can a Company Enter or Leave the Index?
A company can move into the Nasdaq-100 because its market capitalization rises relative to other eligible companies, while another constituent can fall out as its ranking declines.
But market capitalization is not the only consideration. Eligibility, liquidity, listing status and the index’s selection rules all matter.
Nasdaq also has specific procedures for newer companies. Under the current methodology, an eligible company that ranks within the top 40 current constituents by full market capitalization can qualify for a fast-entry process. This can temporarily take the index above 100 constituents before the normal adjustment process restores the target structure.
Initial public offerings also have their own rules. A qualifying IPO is evaluated using an IPO reference date and can generally be added after 15 trading days if the applicable conditions are satisfied.
So the Nasdaq-100 is not simply reviewed once a year and left untouched between December reconstitutions.
Nasdaq-100 vs. Nasdaq Composite
The easiest way to understand the difference is to think about breadth versus concentration.
The Nasdaq Composite is a broad benchmark for eligible securities listed on the Nasdaq Stock Market and represents more than 3,000 companies. It uses total listed market capitalization, so large companies can have substantially more influence than smaller ones.
The Nasdaq-100 is much narrower. It focuses on 100 large non-financial companies and applies additional eligibility and weighting rules.
That means the two indexes can often move in the same direction because they share many large companies. But they are not measuring the same market segment.
If smaller Nasdaq-listed companies rally while the largest non-financial companies remain weak, the Composite can behave differently from the Nasdaq-100. Financial stocks can also contribute to the difference because they are excluded from the Nasdaq-100 but can be represented in the broader Composite.
A useful comparison is therefore:
| Feature | Nasdaq-100 | Nasdaq Composite |
|---|---|---|
| Number of companies | 100 | More than 3,000 |
| Main focus | Large non-financial companies | Broad Nasdaq-listed market |
| Weighting | Modified market capitalization | Total listed market capitalization |
| Financial companies | Excluded | Can be represented if eligible |
| Reconstitution | Annual in December | Broader membership changes as eligible securities enter or leave |
| Quarterly adjustments | Yes | Different maintenance rules |
| Main use | Large-company Nasdaq benchmark | Broad Nasdaq market benchmark |
The difference is especially important when comparing an investment product with the index it is intended to track. A fund linked to the Nasdaq-100 does not have the same exposure as a fund tracking the Nasdaq Composite.
What Industries Are Represented in the Nasdaq-100?
Technology companies have historically been highly visible in the Nasdaq-100, which is why the index is often described as a technology-heavy benchmark.
But technology is not the only industry represented.
Nasdaq’s index description identifies exposure across areas including computer hardware and software, telecommunications, retail and wholesale trade, and biotechnology.
This broader industry mix matters because the Nasdaq-100 is not a pure technology index.
A large move in technology stocks can have an important effect because of their size and representation, but consumer businesses, healthcare companies, communications-related companies and other eligible industries can also influence performance.
The index therefore works better as a benchmark for large, growth-oriented and innovation-focused companies listed on Nasdaq than as a narrowly defined technology gauge.
What Moves the Nasdaq-100?
The biggest companies generally have the greatest influence because of the index’s modified market-cap weighting.
Company earnings are therefore an important source of movement. A strong earnings report, weaker guidance or a major change in expectations can affect an individual constituent and, depending on its weight, the broader index.
Interest rates can also matter. Large growth companies are often valued partly on expectations about future earnings and cash flows, so changes in interest-rate expectations can influence how investors value these businesses.
Economic data, consumer spending, artificial-intelligence investment, semiconductor demand, cloud computing trends and major corporate developments can also affect groups of Nasdaq-100 companies at the same time.
But there is no single factor that explains every daily move.
The index can rise even when some constituents fall because gains among larger companies can outweigh losses elsewhere. Likewise, a sharp decline in a few heavily weighted companies can pressure the index even when many smaller constituents are performing better.
How Investors Track the Nasdaq-100
The Nasdaq-100 itself is an index, not a stock that investors purchase directly.
Investors can instead use investment products designed to track the index, including exchange-traded products, or use the index as a benchmark for comparing portfolio performance.
Nasdaq says the index is tracked by a broad ecosystem of exchange-traded products, futures, options and other financial products. Its 2025 reconstitution report said products linked to the Nasdaq-100 represented more than $640 billion in assets under management across 18 exchanges as of December 31, 2025.
The key point for investors is to check the benchmark behind a product rather than relying on the word “Nasdaq” alone.
A product tracking the Nasdaq-100 can have a very different portfolio from one tracking the Nasdaq Composite, even though both indexes are connected to the same exchange.
Is the Nasdaq-100 the Same as the Nasdaq?
No.
“Nasdaq” can refer to the Nasdaq Stock Market, the company Nasdaq, Inc., or indexes associated with the Nasdaq brand.
The Nasdaq-100 is specifically an index of 100 large non-financial companies that meet its methodology requirements.
The Nasdaq Composite is a much broader index covering thousands of eligible Nasdaq-listed securities.
This distinction matters when reading market reports. A headline saying that “Nasdaq rose” may refer to a particular index rather than the entire exchange or every stock listed there.
For a broader explanation of the market itself, see our guide to Nasdaq.
What the Nasdaq-100 Tells You
The Nasdaq-100 is most useful when you want to understand how a concentrated group of major non-financial Nasdaq-listed companies is performing.
It is not an equal-weighted snapshot of 100 companies, and it is not a complete representation of all stocks traded on Nasdaq.
Its modified market-cap structure means larger companies still carry more influence, while weighting controls prevent the largest constituents from dominating without limits.
Its scheduled rebalances and annual reconstitution also mean that the index evolves as company sizes, eligibility and market conditions change.
That combination gives the Nasdaq-100 a distinctive role: it provides a rules-based way to follow major Nasdaq-listed non-financial companies without simply treating every constituent as equally important.
